Written by Dr. Robert Kowalski — Ph.D. in Agricultural and Biological Engineering from Penn State University, with 18 years of experience in on-farm electrical systems. He has served as an independent damage assessor on farm solar insurance claims involving hail, wind, and fire across the Midwest and Northeast. He is a licensed Professional Engineer and a member of the American Society of Agricultural and Biological Engineers.
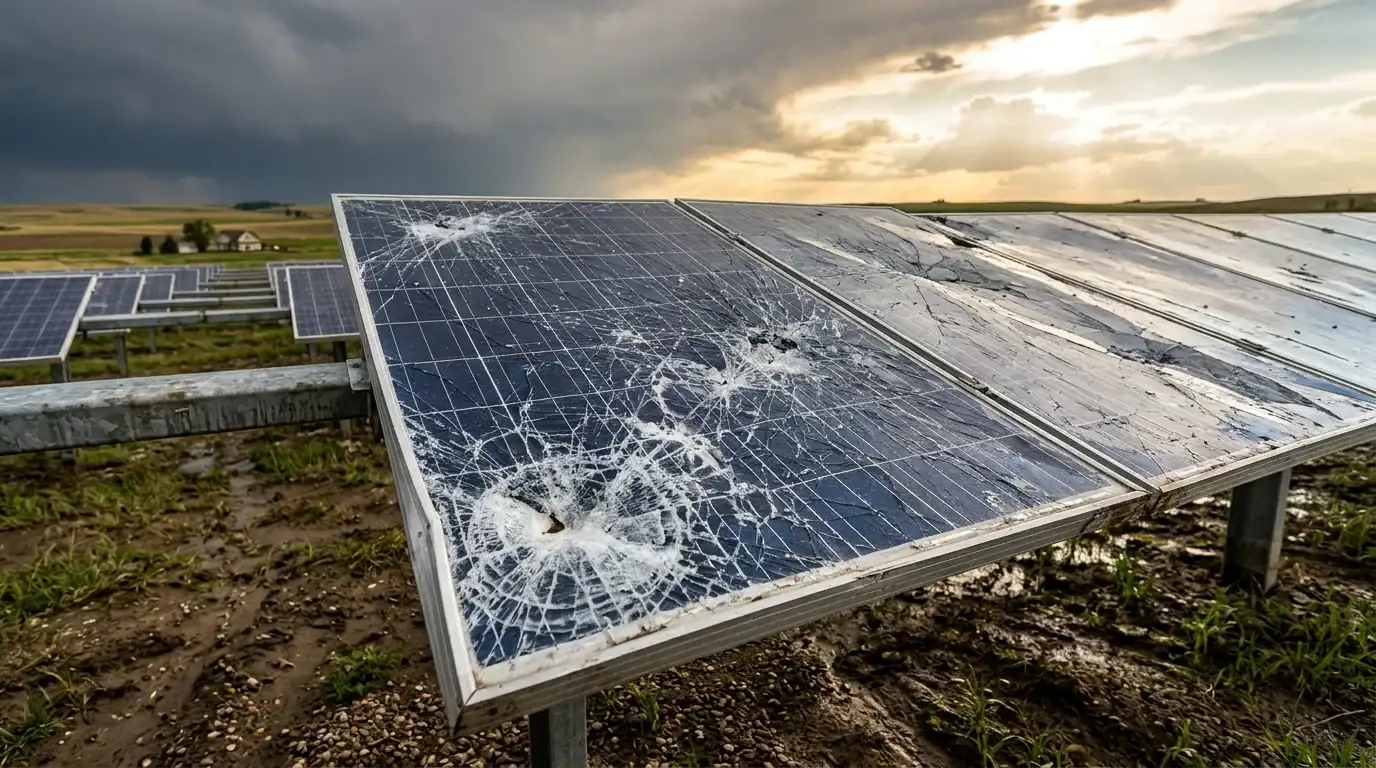
After the same hailstorm, one farmer recovered $0.40 on the dollar for his damaged array. His neighbor, three miles away, recovered full replacement cost. The storm was identical. The paperwork filed before the storm was not. Here is what farm solar claims actually pay — and how to be the second neighbor.
The Problem
Farm solar insurance fails at claim time, not at purchase time. Our insurance guide covers how to get the array covered in the first place; this article covers what happens after the sky falls — because that is where the money is actually lost.
The failure modes repeat with depressing consistency:
- The array was never scheduled. The farm policy’s blanket coverage capped out, or the agent “added it” verbally and the endorsement was never issued. The claim discovers the omission.
- Actual cash value, not replacement cost. A seven-year-old array insured at ACV is depreciated 30–50% before the deductible — the $0.40-on-the-dollar outcome.
- No production baseline. The array “still works” after the storm, so the claim is denied — but output is down 18% from microcracks, and the farmer cannot prove pre-storm production because nobody saved the monitoring data.
- Lost production never claimed. Six months of lost generation during repair is a real, documented loss — and almost never claimed because the farmer did not know the policy covered it.
Every one of these is preventable, and every one is decided before the storm.
What Gets Paid — and What Does Not
| Scenario | Typically paid? | The deciding factor |
|---|---|---|
| Hail-cracked glass, visible damage | Usually yes | Scheduled endorsement + photos of serial numbers on file |
| Microcracks, output down 15–20%, no visible damage | Often denied | Pre-storm production data proving the loss |
| Inverter surge damage from lightning | Usually yes | Grounding documentation; denied if grounding non-code |
| Wind-torn racking | Usually yes | Engineering stamp on the original design wind load |
| Fire (array-caused) | Yes, with investigation | Arc-fault records; installer workmanship documentation |
| Lost production during repair (3–9 months) | Rarely claimed | Business-interruption or loss-of-use rider |
| Theft of panels/copper | Usually yes | Serial number registry filed with insurer |
The Pre-Storm Documentation Package
This is the entire difference between the two neighbors. One afternoon of work, stored in three places (cloud, email, paper file):
1. The schedule. Written confirmation from your insurer that the array is a scheduled structure, with the replacement-cost endorsement, its insured value, and the deductible. One page. If your agent cannot produce it, you do not have it.
2. The baseline. Export 24 months of production data from your monitoring platform — monthly kWh at minimum. After a claim, this is the only acceptable proof of what “normal” looked like. Set a calendar reminder to re-export every 12 months.
3. The photo file. Every panel serial number (one photo per row with serials legible), the racking, the inverter nameplates, the grounding rods and clamps, and wide shots of the whole array. Twenty minutes with a phone. Update after any modification.
4. The paper trail. Installer contract, engineering stamps, electrical permits, inspection sign-offs, and warranty documents. Storm claims on non-permitted or non-inspected systems die on code-compliance grounds.
5. The values. Original installed cost, current replacement quote (refresh every 3–4 years), and your policy’s valuation method — ACV or replacement cost — in writing.
After the Storm: The 72-Hour Sequence
Hour 1–4 — Safety and documentation. Do not touch the array: damaged DC wiring stays live in daylight. Photograph everything from the ground, wide shots first, then detail. Note date, time, and the storm’s NOAA record.
Day 1 — Notify, in writing. Report the claim immediately and in writing; policies contain prompt-notice clauses, and hail claims in the same county are handled in order of filing. State plainly: “This is notice of loss. Full damage assessment to follow.”
Day 1–3 — Get production data before anyone touches anything. Screenshot monitoring output from the storm date forward. If the system is down entirely, that itself is documented loss.
Day 2–7 — Independent assessment before the adjuster’s number. For any claim above ~20,000,hireanindependentassessororengineer(20,000, hire an independent assessor or engineer (500–$2,000) before accepting the adjuster’s figure. Microcrack claims in particular live or die on electroluminescence or IV-curve testing that no adjuster will order voluntarily.
Week 2–6 — Claim the lost production. Multiply lost kWh (baseline minus actual) by your retail rate, monthly, through the repair period. Submit it as part of the claim. Most policies with loss-of-use language owe you this; none will volunteer it.
The Numbers: Two Farms, One Storm
| Item | Farm A (undocumented) | Farm B (documented) |
|---|---|---|
| Array value | $180,000 | $180,000 |
| Valuation method | ACV (40% depreciation) | Replacement cost |
| Production baseline | None | 24 months on file |
| Visible + microcrack damage | Visible only compensated | Both compensated (EL test) |
| Lost production (7 months) | Not claimed | Claimed: $8,900 |
| Net recovery after deductible | $72,000 | $186,400 |
Same hail. Same county. A $114,000 difference produced by one afternoon of paperwork.
Expert Tips
1. Microcracks are the claim that separates prepared farms from the rest. Hail that leaves glass intact can still crack cells invisibly and cut output 10–20% permanently. Without a pre-storm baseline, this loss is unprovable and unpaid. With one, it is straightforward.
2. Replacement cost endorsements expire quietly. Insurers re-underwrite at renewal; a replacement-cost endorsement can silently become ACV. Check the valuation method every renewal, in writing, every year.
3. Grounding documentation wins lightning claims. Lightning claims get denied on “inadequate grounding” more than any other technical pretext. Photographs of your grounding electrodes and clamps — taken on a sunny day, stored off-site — end that argument before it starts. Our grounding guide covers what to photograph.
4. Do not let the insurer total the array cheaply. A 40%-damaged array is often repaired at far less than replacement — which is fine — but confirm the repair quote comes from a qualified solar contractor, not a general roofer with a ladder.
5. Hail rating is a claim-time argument, not a brochure. Panels rated for 1-inch hail at 51 mph (UL 61730) survive most storms; larger stones are “acts of God.” Knowing your panel’s tested rating tells you instantly whether a denial on durability grounds is legitimate.
6. File even when the damage looks small. Hail damage worsens: microcracked cells degrade faster, and late claims on old storms are denied on notice grounds. Document and notify; you can always withdraw.
Conclusion
Solar insurance claims are won before the storm. The farmers who recover full value have five things on file: the schedule, the baseline, the photos, the permits, and the valuation method. The farmers who recover pennies have an agent’s verbal assurance. Spend one afternoon on the documentation package this month — the hail is not going to schedule itself around you.
Frequently Asked Questions
Q: Does farm insurance cover hail damage to solar panels?
A: Only if the array is specifically scheduled on the policy — blanket farm coverage routinely excludes or under-caps solar equipment. With a proper endorsement, hail damage is typically covered; the claim’s success then depends on your documentation: photos of serial numbers, a production baseline, and proof of permitted installation. Claims for invisible microcrack damage are routinely denied without pre-storm production data.
Q: How do I prove lost solar production for an insurance claim?
A: With monitoring data exported before the loss. Monthly kWh figures for 12–24 months establish your baseline; the claim is baseline minus actual output, multiplied by your retail rate, for every month the system is impaired or offline. Without a pre-storm baseline, lost production — often the largest single component of a storm claim — is unrecoverable.
Q: Should I hire a public adjuster for a solar claim?
A: For claims above roughly 20,000,yes—oratminimumanindependentengineer′sassessment(20,000, yes — or at minimum an independent engineer’s assessment (500–$2,000) before accepting the insurer’s number. Public adjusters typically charge 10–15% of the settlement and earn it on technical claims involving microcracks, production losses, or valuation disputes. For simple visible-damage claims under $20,000, thorough documentation usually suffices.
Related Articles
- Farm Solar Insurance: Hail, Wind, Fire, and Liability Coverage Explained — Getting the array properly covered before the storm, including ACV vs. replacement cost.
- How to Ground and Lightning-Proof Your Ground-Mount Solar Array — The grounding documentation that wins lightning claims.
- Solar Panel Degradation and Underperformance on Farms: How to Detect, Diagnose, and Recover Lost Production — Building the production baseline that makes damage provable.
© 2026 Farm Solar Guide. All data sourced from insurance claims documentation, UL 61730 hail rating standards, NOAA storm records, and documented US farm operations. Last verified: November 3, 2026